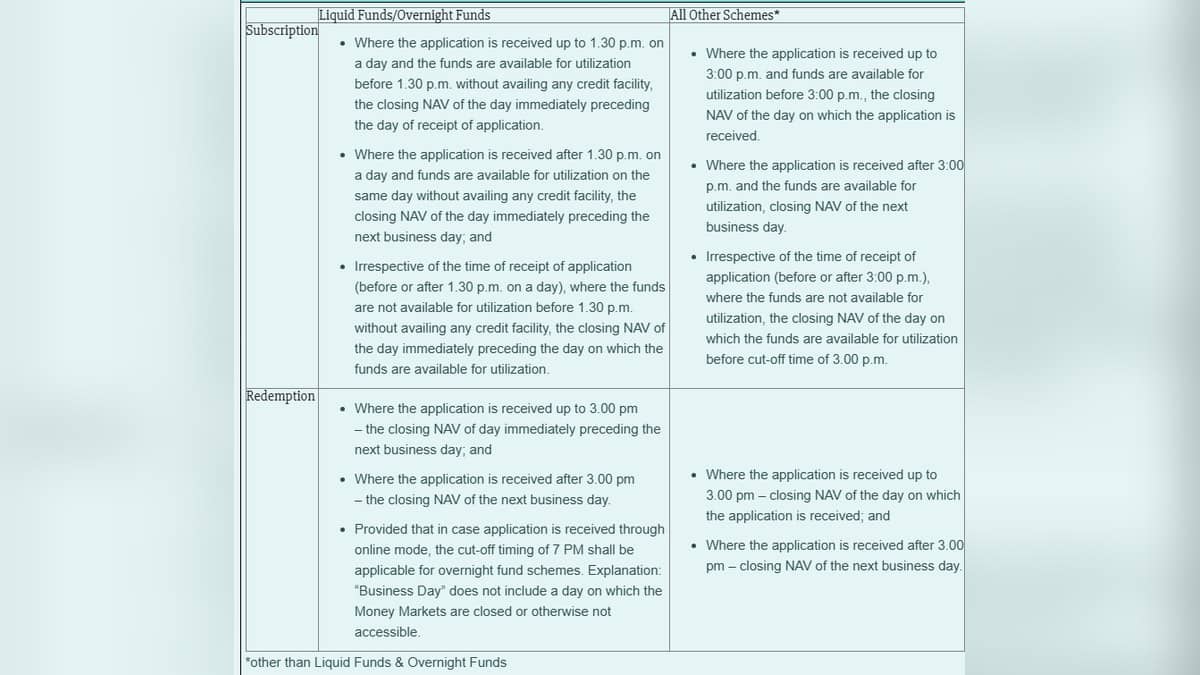
NAV means net asset value. In a mutual-fund account, the NAV shown for a scheme is normally its value per unit: the fund's assets minus its liabilities, divided by the units outstanding. It is a valuation measure. A scheme with a lower NAV is not automatically cheaper or more likely to deliver a higher percentage return.
The unit value also needs a date. AMFI's NAV explainer says fund houses and AMFI publish NAVs daily, with the valuation declared after the trading day closes. A figure copied from an older statement describes that valuation date, not necessarily the value of the holding now.
| Term | Meaning |
|---|---|
| Total assets | Value of the fund's securities, cash and other assets |
| Net assets | Total assets less liabilities |
| NAV per unit | Net assets divided by outstanding units |
| Holding value | Units held multiplied by the relevant NAV, before any redemption adjustment |
How is mutual-fund NAV calculated?
The formula on AMFI's investor-education website includes both sides of the calculation: NAV = (total assets - total liabilities) / total outstanding units. Omitting liabilities would overstate the amount belonging to unitholders.
Consider an invented scheme with securities worth Rs 48 crore, cash of Rs 3 crore and liabilities of Rs 1 crore. Its net assets are Rs 50 crore. If it has 2 crore outstanding units, the NAV is Rs 25. These figures are a worked example, not the holdings or valuation of any named fund.
Suppose its securities subsequently fall to Rs 46 crore while cash, liabilities and unit count remain unchanged. Net assets become Rs 48 crore and NAV becomes Rs 24. A holding of 400 units would move from Rs 10,000 to Rs 9,600. The units have not disappeared; their value has changed.
Does a lower NAV mean a cheaper mutual fund?
SEBI's mutual-fund education FAQ addresses this question directly: comparing the absolute NAVs of similar schemes does not establish which one offers better value. More units for the same amount do not, by themselves, produce a better percentage outcome.
Take two fictional schemes, one with NAV of Rs 20 and another with NAV of Rs 100. Ignoring transaction deductions, Rs 10,000 corresponds to 500 units in the first and 100 units in the second. If both NAVs rise by 5%, they become Rs 21 and Rs 105 respectively.
The resulting holdings are worth Rs 10,500 in each case: 500 × Rs 21 and 100 × Rs 105. If instead both fall by 5%, each holding becomes Rs 9,500. The comparison assumes identical percentage changes solely to demonstrate the arithmetic. It does not suggest that two actual schemes will perform alike.
A statement showing thousands of units can therefore represent a smaller rupee holding than one showing hundreds. The calculation requires both the unit count and its corresponding NAV. Neither number alone tells the whole story.
Is the displayed NAV the amount received on redemption?
AMFI distinguishes the published NAV from a redemption price after an applicable exit load. Its formula is redemption price = applicable NAV × (1 - exit-load rate). The relevant rate and its applicability come from the scheme terms.
For illustration, an applicable NAV of Rs 25 with a 1% exit load gives Rs 24.75 per unit. Redeeming 400 units would produce Rs 9,900 before any other applicable adjustment. Without that assumed load, units multiplied by NAV would be Rs 10,000. The Rs 100 difference is the illustrative load, not a fall in NAV.
A useful statement check is to read the scheme name, unit count and valuation date together, then reproduce units × NAV. A historical percentage change can be calculated as (ending NAV / starting NAV - 1) × 100, but that simple calculation alone does not account for separate distributions or multiple cash flows.
For related coverage, read our explanation of SEBI's mutual-fund portfolio route, the effect of repo-rate changes on deposits and loans and education-loan eligibility and interest support.